SIMPLY 3 FINSERV PRIVATE LIMITED [CIN: U67190PB2022PTC056099] is an AMFI Registered Mutual Fund Distributors & SIF Distributor (ARN-249158)
Lokesh Malhotra [ARN-158405] | AMFI Registered Mutual Fund Distributor
How Indian households are evolving their approach to savings and investments
For generations, the first instinct of an Indian household has been simple: save for safety.
Keep money in the bank. Buy gold. Own property. Build a financial cushion.
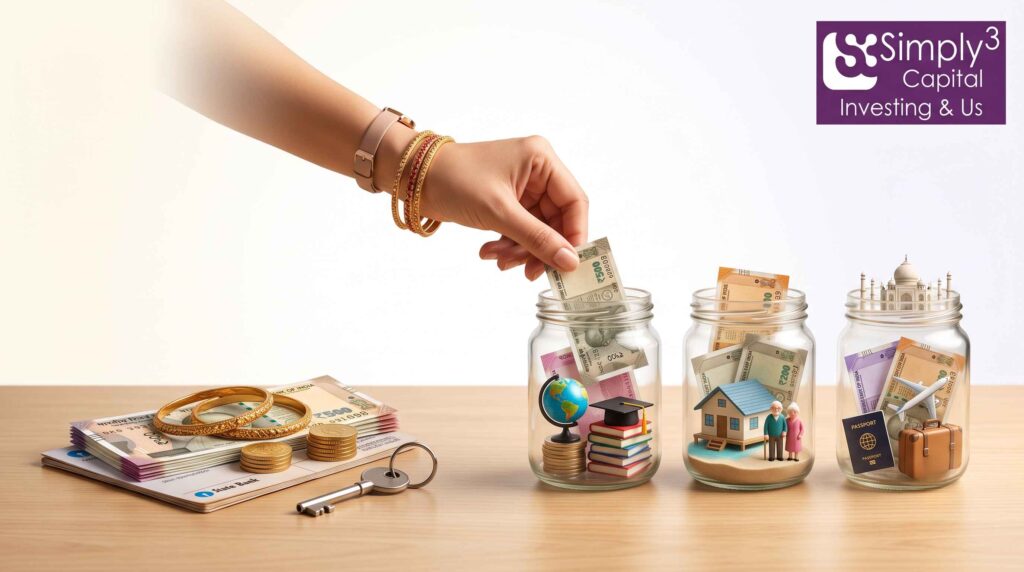
That approach continues to have relevance. But a gradual change is underway. Increasingly, households are looking beyond simply saving money and thinking about what different pools of money are meant to achieve.
Recent data points to this broader financialisation of household savings. Between March 2020 and March 2025, managed investment categories—including mutual funds, insurance, pension funds, PMS and AIFs—grew from about ₹98 lakh crore to ₹219 lakh crore. During the same period, bank deposits increased from approximately ₹130 lakh crore to ₹226 lakh crore.
The numbers suggest an important point: traditional savings are not necessarily being replaced; households are increasingly adding financial investments alongside them.
From One Savings Bucket to Multiple Needs
A household may need money for very different purposes.
An emergency reserve may require liquidity and accessibility. Protection needs may call for insurance. Money intended for a longer time horizon may be considered for market-linked investments, depending on the investor's circumstances.
This is where the idea of purpose-based investing becomes relevant.
Mutual funds offer different categories across equity, debt and other permitted securities, allowing investors to consider options based on their investment objective and time horizon. However, the appropriate choice depends on the individual investor's circumstances, including risk profile, investment objective and time horizon.
The Shift Is Also Visible in Household Data
The Economic Survey 2025-26 notes that the share of equity and investment funds in household financial assets increased from 15.7% in March 2019 to 23% by March 2025. It also highlights the rising participation through systematic investments, while noting that the changing pattern reflects diversification rather than complete displacement of traditional deposits.
This distinction matters.
The objective need not be to move money from one product to another simply because a particular investment category is becoming popular. Instead, investors can consider what the money is for, when it may be required and what level of market fluctuation they can reasonably accommodate.
Investing With Purpose Requires Awareness
Greater participation in market-linked investments also brings greater responsibility.
Mutual fund investments are not guaranteed or assured-return products. Their value can fluctuate, and investors may lose part or all of their invested capital. Past performance does not guarantee future performance.
Therefore, the evolution from saving to investing should not simply be about seeking higher returns. It should be about becoming more informed, more purposeful and more disciplined in handling money.
The Bigger Change
India's household savings story is evolving.
The question is gradually moving from:
“Where should I keep my money?”
to:
“What is this money intended for, and what investment approach may be appropriate for that purpose?”
That shift—from saving for safety to investing with purpose—can encourage greater financial awareness and more deliberate decision-making.
This article is for general informational and educational purposes only and should not be construed as investment advice, a recommendation, solicitation or an offer to buy or sell any mutual fund scheme or other investment product. Mutual fund investments are subject to market risks, including possible loss of principal. Investors should consider their investment objectives, risk profile, time horizon and applicable scheme-related information before investing. Past performance is not indicative of future results.
Follow us on: