SIMPLY 3 FINSERV PRIVATE LIMITED [CIN: U67190PB2022PTC056099] is an AMFI Registered Mutual Fund Distributors & SIF Distributor (ARN-249158)
Lokesh Malhotra [ARN-158405] | AMFI Registered Mutual Fund Distributor
Factor investing may sound technical, but the basic idea is quite simple.
Think about food. A meal contains different ingredients, but our body benefits from the nutrients within those ingredients—such as protein, carbohydrates, vitamins and minerals.
Similarly, instead of looking only at individual stocks, factor investing looks at specific characteristics of companies that have historically been associated with differences in returns and risk.
These characteristics are called factors.
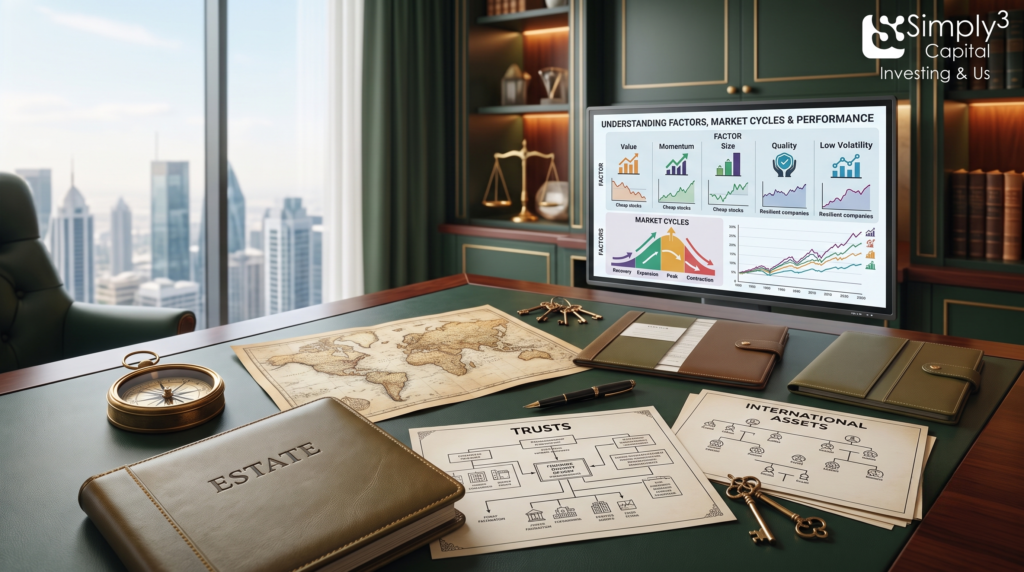
Four widely discussed equity factors are Value, Momentum, Quality and Low Volatility.
Understanding these factors—and how they behave in different market environments—is important before considering any factor-based investment approach.
What Are the Major Factors?
1. Value
Value focuses on companies that appear relatively inexpensive compared with measures such as earnings, book value or sales.
The underlying idea is that markets may sometimes price companies below what their fundamentals might suggest.
However, a low valuation does not automatically mean a company will perform well. A company can remain inexpensive for a long time if its business fundamentals continue to weaken.
Value can therefore experience long periods of underperformance.
2. Momentum
Momentum focuses on securities that have demonstrated relatively strong recent price performance.
The idea is based on the observation that market trends can persist for some time.
Momentum can perform well when established trends continue. However, when market leadership changes suddenly, momentum strategies can experience sharp reversals.
3. Quality
Quality generally focuses on companies with characteristics such as stronger profitability, healthier balance sheets and more stable earnings.
Quality-oriented strategies may be relatively resilient when investors become more selective about business fundamentals.
However, quality companies can also become expensive, and a high-quality business is not necessarily a high-return investment at every price.
4. Low Volatility
Low Volatility focuses on companies whose share prices have historically experienced relatively lower fluctuations.
The objective is not to eliminate losses.
Instead, the approach seeks exposure to stocks that have historically exhibited lower volatility than the broader market.
Low Volatility can potentially behave differently from aggressive parts of the equity market, particularly during periods of market stress. However, it may lag when high-beta and highly volatile stocks lead a strong market rally.
How Do Factors Behave in Different Market Cycles?
One of the most important things to understand about factor investing is that no factor performs consistently in every market environment.
Market cycles can influence the relative performance of different factors.
| Market Environment | Value | Momentum | Quality | Low Volatility |
| Bull Market | Can benefit when economically sensitive/value stocks participate strongly | Can benefit from persistent market trends | May participate through financially stronger businesses | May lag aggressive rallies |
| Bear Market | Can remain under pressure if weaker businesses deteriorate | Can experience sharp reversals when trends break | May show relative resilience | May offer relatively defensive characteristics |
| Recovery | Can benefit when beaten-down valuations recover | Can benefit once a new trend develops | May continue to favour financially stronger businesses | Can lag a sharp risk-on recovery |
| Sideways Market | May benefit when valuation differences normalise | Can struggle when trends frequently reverse | May provide relatively stable exposure | May appeal to investors seeking lower historical volatility |
These are historical tendencies, not predictions.
The same factor can behave differently across different periods, countries and market conditions.
What Does Long-Term History Tell Us?
Factor investing is supported by decades of academic and market research.
Studies of long-term global equity markets have identified persistent historical relationships between factors and investment returns. Research such as the Fama-French framework helped establish the importance of systematic characteristics in explaining differences in stock returns.
Research covering international markets has also documented long-term premiums associated with factors such as Value and Momentum.
However, long-term historical returns should not be confused with consistent annual outperformance. This distinction is critical.
A factor may deliver a positive premium over a very long period while still experiencing several years of disappointing performance along the way.
For example, Value has historically experienced significant periods of underperformance before recovering. Momentum can experience sudden drawdowns when established trends reverse. Quality and Low Volatility can also go through periods when other market segments perform better.
Therefore, factor investing requires investors to look beyond one-year or even three-year performance.
Returns and Volatility: Two Sides of the Same Picture
Investors often look at returns first.
But when evaluating factors, volatility is equally important.
Two strategies can produce similar long-term returns but experience very different journeys.
A factor strategy may deliver attractive long-term results while experiencing substantial periods of volatility and underperformance.
This creates an important behavioural challenge.
An investor who enters a factor strategy after a period of strong performance may become disappointed when the cycle changes.
For example:
Strong factor performance → increased investor interest → factor cycle changes → underperformance → investor exits → eventual recovery.
This is why historical factor investing should be understood through a full market-cycle perspective, rather than by looking only at recent returns.
The Key Takeaway
Factor investing is not about finding a factor that will outperform every year.
It is about understanding specific characteristics that have historically influenced investment outcomes.
Value, Momentum, Quality and Low Volatility each have different characteristics, different drivers and different periods of strength and weakness.
Their historical experience also shows an important reality:
Factors can underperform for extended periods.
Long-term historical returns therefore need to be considered alongside volatility, drawdowns, investment horizon and the ability to remain invested through different market environments.
The next question naturally follows:
If individual factors can go through long periods of underperformance, can combining different factors create a more balanced investment approach?
That is where multi-factor investing becomes relevant—and will be explored separately.
Investor Disclosure
For investor education and awareness only. This article is not investment advice, financial planning, a recommendation, solicitation or an offer to buy or sell any security or investment product.
Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully.
Past performance is not indicative of future results. Historical factor returns and market-cycle observations do not guarantee similar future performance. Investors should consider their investment objective, risk profile, time horizon and other relevant circumstances before making investment decisions.
Follow us on: